How do Credit Cards Work? - The Definitive New Zealand Guide
Our guide takes you through the basics of a credit card, explaining low fee, low interest, balance transfers, cashback and rewards, helping you make the right decision.
Updated 31 August 2026
Important: This guide was relaunched in August 2026. Every rate and fee was checked against each issuer's published terms. Issuers can change these at any time, so confirm the details on the issuer's site before you apply. Report an error on this page - no name or email needed.
With 60+ different credit cards available, it’s perfectly reasonable to be confused about which one suits your spending habits, or if you need a credit card at all.
This guide takes you through the basics of a credit card, explaining low fee, low interest, balance transfers, cashback cards and rewards to help you pick the best card and avoid the many undesirable cards lurking around.
Important: This guide was relaunched in August 2026. Every rate and fee was checked against each issuer's published terms. Issuers can change these at any time, so confirm the details on the issuer's site before you apply. Report an error on this page - no name or email needed.
With 60+ different credit cards available, it’s perfectly reasonable to be confused about which one suits your spending habits, or if you need a credit card at all.
This guide takes you through the basics of a credit card, explaining low fee, low interest, balance transfers, cashback cards and rewards to help you pick the best card and avoid the many undesirable cards lurking around.
Credit Card Must-Know Facts:

|
What is a Credit Card?A credit card is a payment card that lets you spend by borrowing from the card supplier, who then sends you a bill at the end of every month.
All credit cards have a “credit limit” - this is the maximum amount you can borrow. Your credit limit depends on your income, credit score and general financial health. Not everyone who applies for a credit card is given one - many factors beyond your income are taken into consideration. If you spend with a credit card, you will be charged interest. However, if you pay back what you borrowed to spend by the due date, the interest is zero. Purchase rates run from 9.95% on the cheapest low interest card to 22.95% on rewards cards, and 28.95% to 29.49% on store cards. |

|
Who can get a Credit Card?Anyone over 18 years of age can apply for a credit card. Applicants with little or no income are usually offered a low limit, if approved at all. Working adults will have greater choices as to credit limits and benefits. You can apply for more than one credit card; your chance of success depends on your credit history and financial standing.
|

|
What is a “Balance Transfer” credit card, and how does it work?To be eligible for a balance transfer credit card, you need to have an existing credit card with money owing. A balance transfer credit card is a new credit card that allows for an existing card’s balance to be transferred to it.
The purpose of the balance transfer credit card is that it offers a low interest rate (or 0% in some cases) so you can repay it with much less interest cost than your existing credit card. Balance transfer credit cards are suitable for people having some difficulty in repaying their credit card every month. By paying low or no interest, the total debt can be paid off faster. |

|
How do “0% interest rate” credit cards work?0% interest is also known as 'interest free'. You can make purchases on the card and pay no interest for a set period of time (i.e. until the balance is due). As is the case in New Zealand, GEM Visa and Q Mastercard both offer extended 0% periods beyond the standard 44 to 55 interest-free days offered by traditional credit cards.
0% interest offers are advertised to entice people to sign up and incur debt. But they do have their place - if you want to make a large purchase and pay for it over a set period, such as six months, they can make the purchase much cheaper than a short-term loan etc. But only if it's repaid in full at the end of the interest-free period. If you don’t do this, the remaining debt becomes expensive. |

|
How do cashback, rewards and Airpoints credit cards work?Cashback credit cards pay you to spend on them. While it’s not a large amount, you can expect around 65 to 85 cents back per $100 spent - $65 to $85 on $10,000 - before the annual fee.
Rewards cards earn points or Airpoints on every dollar you spend - typically 1 Airpoint per $70 (AMEX) to $110 (ANZ, Westpac), or Membership Rewards points that convert to Airpoints or Qantas Points. Annual fees run from $0 to $195, and the value is rarely more than 1.5% of what you spend. Important: Cashback or rewards, the rule is the same: the card only makes sense if you pay the balance in full every month and spend enough to cover the fee. If you don't, the interest wipes out the rewards many times over. |
|
MoneyHub Founder Christopher Walsh shares his views about credit cards:
"Banks (arguably) offer credit cards aggressively to their customers, and credit card debt is expensive. Per Reserve Bank data we analyse, the average rate on interest-bearing credit card balances is around 20% p.a. New Zealanders owe around $6 billion on credit cards, about half of it incurring interest, and pay around $550 million a year just servicing it. I receive emails every week from everyday New Zealanders who are in a credit card debt trap. It's a terrible situation to be in, and I urge anyone paying interest on a credit card to pay down and/or cancel their credit card. Credit cards can mean long-term debt and a lot of hassle - please be careful before deciding to get one. For more information, I explain how credit cards work in the video below:" |
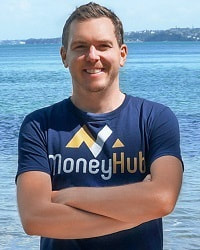
Christopher Walsh
MoneyHub Founder |
The 12 Sacred Rules of Credit Cards:

|
Credit Cards are Very Expensive if Not Paid OffMaking the minimum payment will mean the remainder of the balance will be charged a huge amount of interest. For example, taking 12 months to pay off a $4,000 balance in equal instalments costs around $450 in interest at 20% p.a. - and paying only the minimum costs many times that.
|

|
If you don’t pay a minimum payment, there are more fees comingLate payment fees are just the start. Your card will also go to the collections department of your credit card issuer, meaning a lot of hassle and contact to get the balance.
|

|
Credit cards cannot be paid off with other credit cardsYou can't pay a credit card bill with another credit card. The only way to move debt between cards is a balance transfer; otherwise the balance is paid from your bank account.
|

|
Charge only what you can afford to pay offBe happy and live within your means. If you can’t afford it in four weeks, don’t buy it.
|

|
You can move your credit card debt if you need toThere is no obligation to stay with a credit card if you are being charged more than you need to be. Look for a balance transfer deal which will at least reduce the interest costs.
|

|
But, don't get too excited by balance transfersThe debt you incurred and transferred still needs to be paid. Low or zero interest doesn’t last forever, so paying off a card is a big priority.
|

|
Choose cards like a winnerLow-interest credit cards are perfect if you sometimes can’t pay them off, or look for generous rewards and flight benefits if you always pay your credit card on time.
|

|
Avoid being a slave to rewards and perks that aren't worth the costDon’t spend more thinking it will make you better off - the benefits from a credit card are rarely above 1.5% of what you spend, so don’t get caught out overspending.
|

|
Don't get too many credit cardsThe more cards you have, the more temptation you might have to use them. Also, having several cards is harder to manage and budget for. So keep it light and simple with one or two cards max.
|

|
Audit your statement every monthA credit card often has things in it you don’t need to pay for, like automatic renewals you don’t want or memberships you don’t need. Don’t be afraid to relive the past: go line by line through your bill and highlight anything that’s wrong or you can live without.
|

|
Don’t withdraw cash on your credit cardThe interest is high, and you get charged it from the minute you take it out of the machine. Also, you don’t earn any rewards or cashback on it.
|

|
Don't use credit cards if you will abuse themIf you don’t have self-control, stick with cash. Buying stuff may seem like a good idea, but debt can spiral and cause misery. Be smart; be safe.
|
